
Over the past decade, Canadian homeowners have watched their property values skyrocket, turning modest homes into powerful sources of wealth. Enter the Home Equity Line of Credit, or HELOC: a financial tool that has become wildly popular. Used wisely, it is a lifeline. Used recklessly, it can turn dreams of prosperity into a mountain of debt.
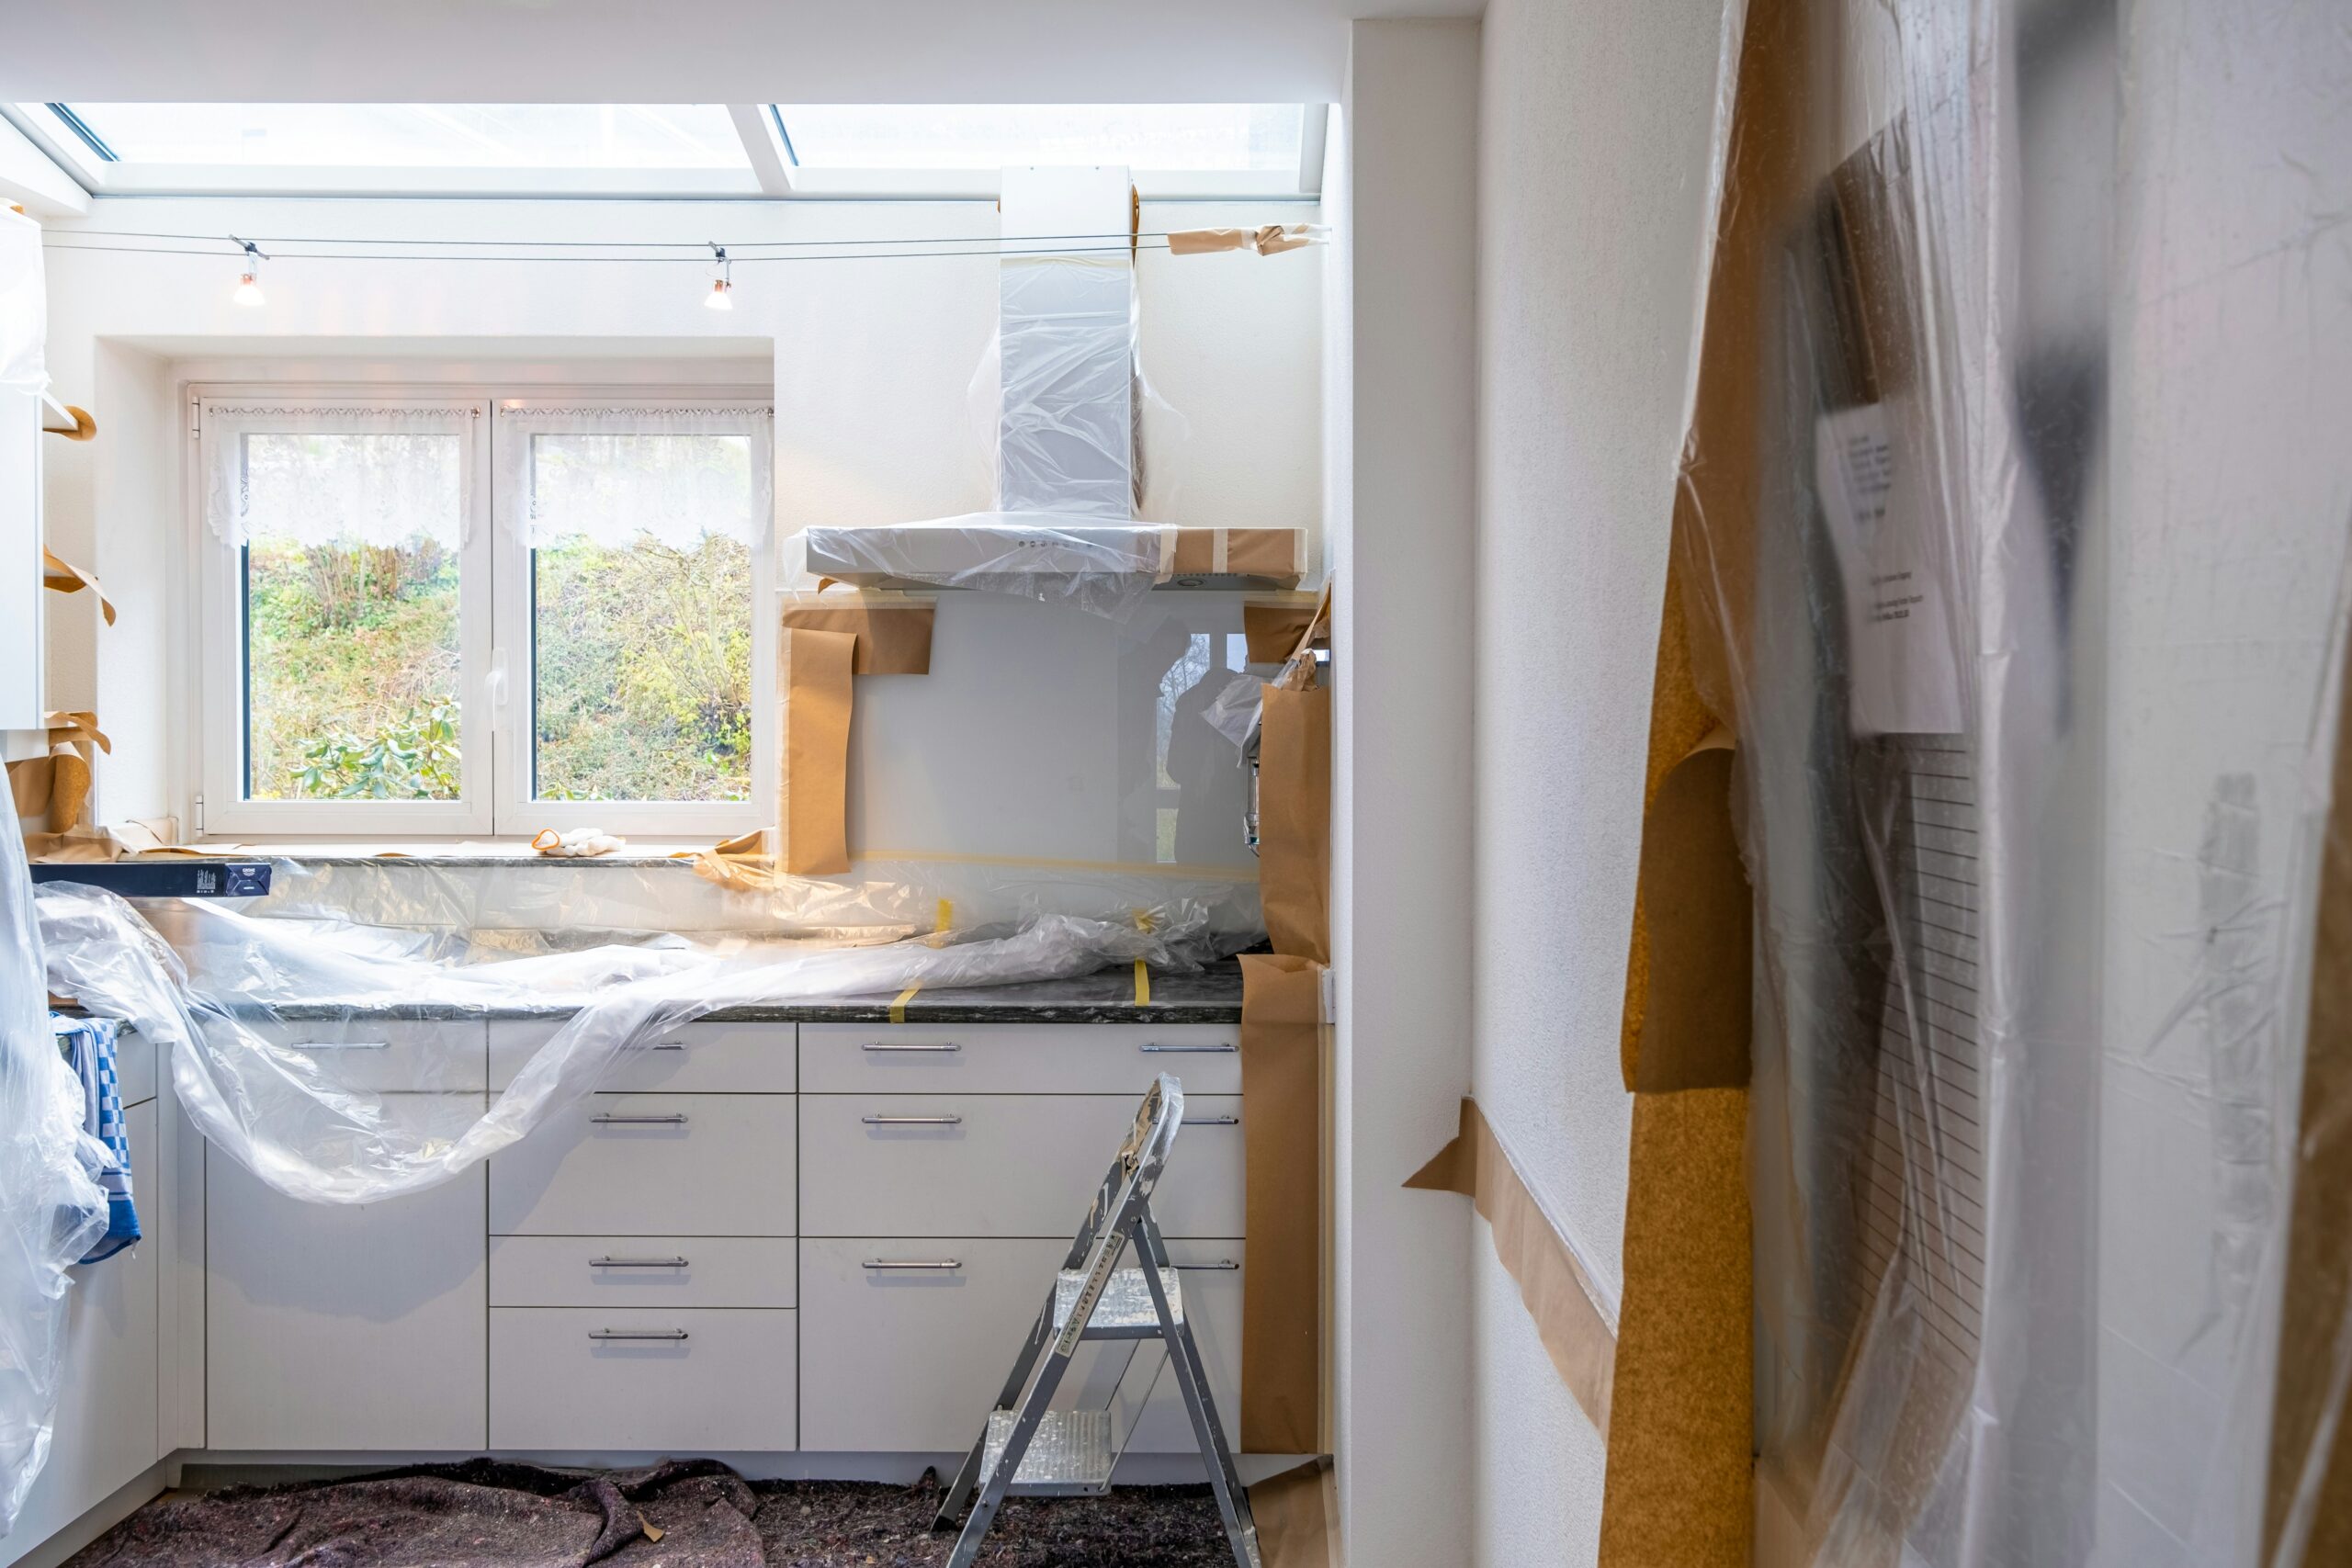
Think of a HELOC as a revolving tap on your home’s equity, usually at far lower interest rates than credit cards. Canadians are using these lines for everything from kitchen makeovers and tuition bills to investment opportunities and to help their kids break into the real estate market. You pay interest only on what you use, making it a flexible, affordable way to juggle expenses or seize opportunities on your own terms.
When managed responsibly, HELOC can fund smart renovations or serve as a quick safety net in emergencies, often with less hassle than other loans. It is easy to fall into the trap of treating your home equity as a bottomless ATM for vacations and splurges that will not pay you back.
Many HELOCs require only interest payments, so balances can remain outstanding for years. Most have variable rates, meaning your payments could jump if interest rates rise. If home values drop, your equity could erode faster than you think, making refinancing or selling much tougher than planned.
A HELOC is a tool, not a windfall. Use it for projects that build your wealth, not to fund everyday spending. Always have a payback plan and avoid the minimum-payment trap. Keeping a buffer of unused equity can protect you if the market turns suddenly.
If your HELOC is almost maxed out, consider transferring part of the balance to a fixed-rate loan so you are paying down what you owe, not just treading water. If payments are tight, consolidating your HELOC and mortgage into a single, simple loan with a clear payoff schedule can give your finances much-needed breathing room, and peace of mind. If you rarely use your HELOC, lock the account at its full limit. You will need to call the lender to unlock it, an extra hurdle that curbs impulse spending and helps thwart would-be fraudsters, too.
Tempted to use your HELOC for a vacation? Here is a smarter approach: invest the funds first, in a second mortgage or another income-generating asset and use the returns to fund your trip. Borrow at 5%, invest at 12%, and the profit can cover your adventure (sometimes with the bonus of tax-deductible interest). Let your home’s equity work for you, not against you.
During the pandemic, homeowners rushed to use HELOCs to buy investment properties or to take out second mortgages, riding the wave of cheap money and soaring home prices. Now, with rates up and prices down, the landscape has shifted, and not in borrowers’ favour. Some lost their entire investment in second mortgages when falling home values left insufficient equity to cover both loans. Others who used HELOCs to buy pre-construction properties found themselves scrambling when appraisals came in below the purchase price, forcing them to cover large shortfalls just as their property values fell and HELOC payments spiked. In this risky market, one wrong move can topple your financial house of cards. Do your research and tread carefully.
HELOCs offer both freedom and risk. The borrowing boom has opened doors, but also traps. With discipline, a HELOC can help you build, invest, and weather storms. Used thoughtlessly, it can turn your home’s value into a lifelong financial drag.
Let your home be a launchpad for wealth, not a bottomless pit for spending. Use your HELOC with purpose, discipline, and a clear plan.
Stay in the loop with exclusive news, stories, and insights—delivered straight to your inbox. No fluff, just real content that matters. Sign up today!